
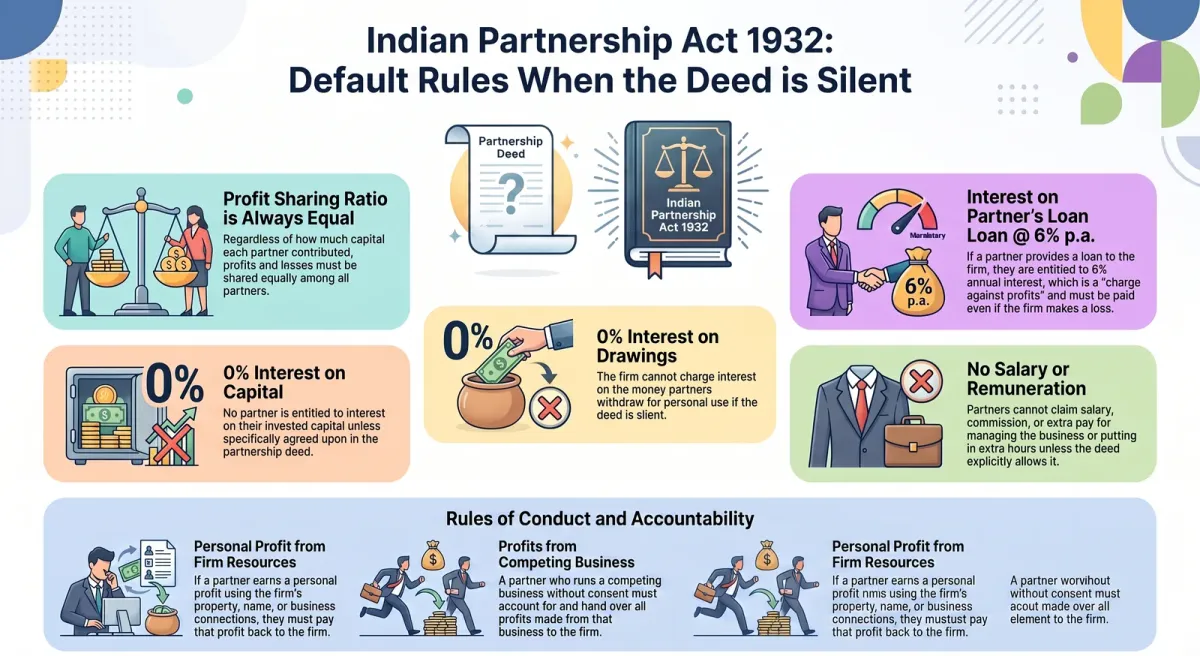
Not every partnership firm operates with a perfectly drafted partnership deed. Sometimes partners start a business informally, or the deed simply doesn’t address a particular issue that comes up later — like whether a partner should get a salary, or how much interest is payable on a partner’s loan to the firm. This is exactly where the Indian Partnership Act, 1932 steps in with a set of default rules. For CBSE Class 12 Accountancy students, understanding these provisions is essential, because they directly decide how a firm’s Profit and Loss Appropriation Account is prepared whenever the deed is incomplete or absent.
Why These Provisions Matter for Accounting
A partnership deed is the primary document governing the relationship between partners. But wherever it is silent on a matter, the Act’s provisions automatically fill the gap. Accountants must know these default rules cold, because board exam questions frequently test scenarios where “no partnership deed exists” or “the deed is silent on this point.”
Key Provisions Relevant to Accounting
1. Profit Sharing Ratio
If the deed does not specify how profits and losses should be split, the Act says they must be shared equally by all partners — regardless of how much capital each partner has contributed. This often surprises students, since it feels intuitive that a partner who invested more capital should get a larger share of profit. But under the Act, capital contribution and profit share are not automatically linked.
2. Interest on Capital
No partner has an automatic right to interest on the capital they’ve invested in the firm. Interest on capital is allowed only when the partners have expressly agreed to it. If the deed is silent, no interest on capital is payable at all — not even at a nominal rate.
3. Interest on Drawings
Just as with capital, no interest is charged on a partner’s drawings unless the deed specifically provides for it. In the absence of an agreement, drawings are treated as interest-free withdrawals.
4. Interest on Partner’s Loan
This is one provision where the Act does specify a rate. If a partner has advanced a loan to the firm (separate from their capital contribution) for business purposes, they are entitled to interest at 6% per annum, even if the deed is silent. Unlike interest on capital, this interest on loan is treated as a charge against profits, meaning it must be paid whether the firm earns a profit or incurs a loss.
5. Remuneration for Firm’s Work
No partner is entitled to a salary, commission, or any other form of remuneration for participating in the firm’s business, unless the partnership deed specifically provides for it. Simply putting in extra hours or managing a department doesn’t automatically entitle a partner to compensation beyond their profit share.
Other Important Provisions Under the Act
Beyond these five accounting-relevant rules, the Act also lays down duties that apply “subject to contract between the partners” — meaning the deed can override them, but if it doesn’t, these apply by default:
-
Personal profit from firm’s property or name: If a partner earns any personal profit by using the firm’s property, business connections, or the firm’s name, they must account for that profit and hand it over to the firm.
-
Competing business: If a partner runs a business of the same nature that competes with the firm, without the consent of the other partners, they must account for and pay over to the firm any profit made from that competing business.
These provisions exist to protect the firm from partners who might otherwise misuse their position for personal gain.
A Quick Reference Table
| Issue | If Deed Is Silent |
|---|---|
| Profit-sharing ratio | Equal share for all partners |
| Interest on capital | Not allowed |
| Interest on drawings | Not charged |
| Interest on partner's loan | 6% p.a., charge against profits |
| Salary/commission to partners | Not allowed |
Key Takeaways
-
The Indian Partnership Act 1932 provides default rules that apply only when the partnership deed is silent on a matter.
-
Interest on a partner’s loan (6% p.a.) is the only interest-related provision the Act mandates by default.
-
No partner automatically earns a salary, commission, or interest on capital without an express agreement.
-
Profits, in the absence of an agreement, are always shared equally — irrespective of capital contribution.
Master These Rules With Practice
These default provisions show up repeatedly in CBSE board exam case-study and short-answer questions. Visit https://app.championsprep.in for topic-wise practice questions and mock tests on Partnership Basic Concepts, built for Class 11–12 Commerce students preparing for boards and entrance exams like CUET and IPMAT.
Test Your Knowledge
Indian Partnership Act 1932: Key Provisions for Accounting (Class 12 Guide)
Frequently Asked Questions
If a partnership deed is silent about interest on capital, will a partner still get it? +
No. Interest on capital is allowed only when it is expressly agreed to by the partners. If the deed is silent, no interest on capital is paid at all.
What rate of interest is a partner entitled to on a loan given to the firm, if the deed doesn't mention a rate? +
Under the Indian Partnership Act, 1932, a partner is entitled to interest at 6% per annum on any loan advanced to the firm, even without an agreement.
Can a partner claim a salary for managing the business if the deed says nothing about it? +
No. No partner is entitled to a salary or other remuneration for taking part in the firm's business unless the partnership deed specifically provides for it.
How are profits shared if there is no partnership deed at all? +
Profits and losses are shared equally among all partners, irrespective of the amount of capital each partner has contributed.
What happens if a partner earns personal profit using the firm's business connections? +
As per the Act, that partner must account for such profit and pay it over to the firm, unless the partners have agreed otherwise.
AI-powered practice — free to start