
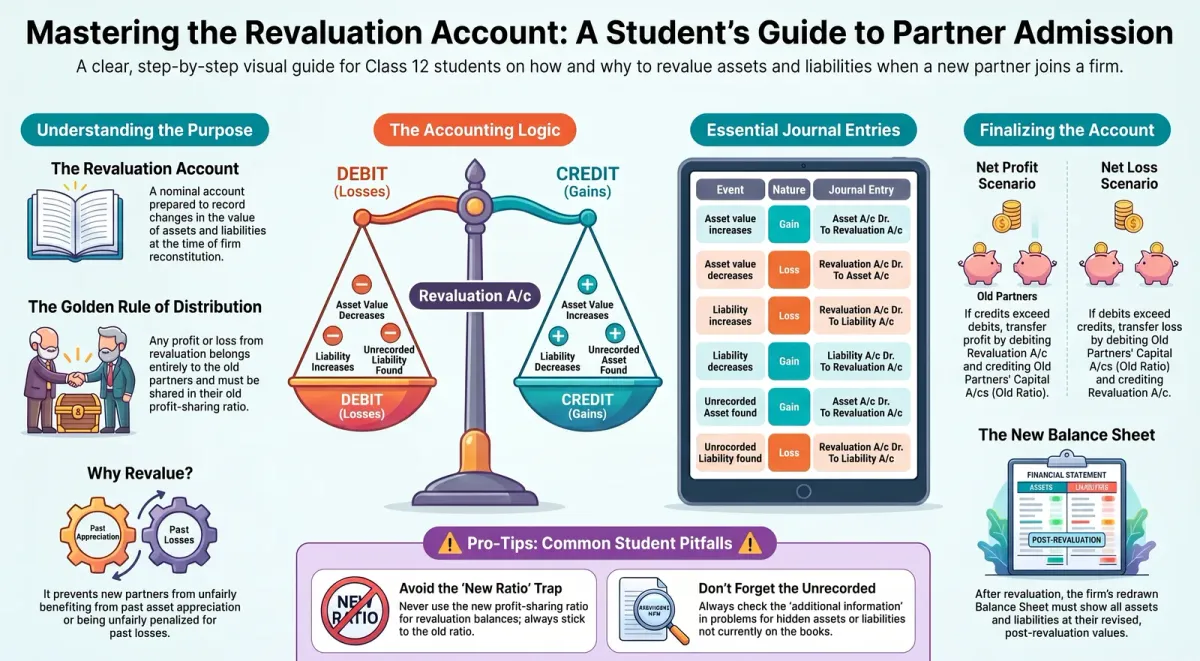
Before a new partner joins a firm, it’s only fair that the firm’s assets and liabilities reflect their true current worth — not outdated book values from years ago. This is the purpose of the Revaluation Account, a topic that appears in nearly every admission-of-partner numerical problem in CBSE Class 12 Accountancy.
Why Is Revaluation Necessary?
Imagine a firm bought machinery years ago for Rs. 10 lakh, now worth Rs. 15 lakh. If a new partner joins without revaluing this asset, they’d unfairly share in that Rs. 5 lakh appreciation, even though it happened before their time. The reverse also applies: if an asset has lost value or a liability is understated, the old partners should bear that loss, not the incoming one.
The golden rule: any profit or loss from revaluation belongs entirely to the old partners, in their old profit sharing ratio — never to the new partner.
What Is the Revaluation Account?
The Revaluation Account (sometimes called the Profit and Loss Adjustment Account) is a nominal account prepared specifically to record all changes in the value of assets and liabilities at the time of reconstitution. Once every adjustment is recorded, the account’s balance — representing net profit or net loss on revaluation — is transferred to the old partners’ capital accounts.
Journal Entries for Revaluation
Six types of adjustments typically arise, each with its own entry:
| Adjustment | Nature | Entry |
|---|---|---|
| Increase in value of an asset | Gain | Asset A/c Dr. To Revaluation A/c |
| Decrease in value of an asset | Loss | Revaluation A/c Dr. To Asset A/c |
| Increase in amount of a liability | Loss | Revaluation A/c Dr. To Liability A/c |
| Decrease in amount of a liability | Gain | Liability A/c Dr. To Revaluation A/c |
| Unrecorded asset discovered | Gain | Asset A/c Dr. To Revaluation A/c |
| Unrecorded liability discovered | Loss | Revaluation A/c Dr. To Liability A/c |
Notice the pattern: anything that increases firm value is credited to the Revaluation Account (a gain); anything that decreases firm value is debited to it (a loss).
Transferring the Final Balance
Once all adjustments are posted, the Revaluation Account is balanced off. A credit balance (net profit) is transferred by debiting Revaluation A/c and crediting Old Partners’ Capital A/c (old ratio). A debit balance (net loss) is transferred by debiting Old Partners’ Capital A/c (old ratio) and crediting Revaluation A/c.
Worked Example
P and Q are partners sharing profits 3:2. They admit R into the firm. On the date of admission: Stock (book value Rs. 60,000) is reduced by 10%; Machinery (book value Rs. 1,00,000) is appreciated by 5%; a provision for doubtful debts of Rs. 2,000 is created; and an unrecorded liability of Rs. 3,000 is brought into the books.
| Item | Amount | Nature |
|---|---|---|
| Stock decrease (10% of 60,000) | Rs. 6,000 | Loss |
| Machinery increase (5% of 1,00,000) | Rs. 5,000 | Gain |
| Provision for doubtful debts | Rs. 2,000 | Loss |
| Unrecorded liability | Rs. 3,000 | Loss |
Total losses (Rs. 11,000) exceed total gains (Rs. 5,000), giving a net loss of Rs. 6,000, shared by P and Q in their old ratio 3:2 — P bears Rs. 3,600 and Q bears Rs. 2,400. The transfer entry: P’s Capital A/c Dr. 3,600, Q’s Capital A/c Dr. 2,400, To Revaluation A/c 6,000.
After Revaluation: What Happens to the Balance Sheet?
Once the Revaluation Account entries are posted, the firm’s balance sheet is redrawn showing all assets and liabilities at their revised (post-revaluation) values — not the original book values. This revised balance sheet becomes the new starting point for the reconstituted firm going forward, with the new partner included.
A Note on “Revaluation” vs “Memorandum Revaluation”
If partners want assets and liabilities to continue appearing at their original book values, a Memorandum Revaluation Account can be used instead, achieving the same profit/loss distribution without permanently changing recorded values. For CBSE Class 12 problems, however, the standard Revaluation Account is the default unless stated otherwise.
Common Mistakes to Avoid
-
Sharing revaluation profit/loss in the new ratio instead of the old ratio — this is the single most common error students make.
-
Forgetting unrecorded assets or liabilities mentioned in the additional information of a question.
-
Mixing up which side an item goes on — always ask: does this increase or decrease the firm’s net worth?
-
Not updating the balance sheet with revised values after preparing the Revaluation Account.
Quick Recap
Revaluation ensures assets and liabilities reflect true current values before a new partner joins, with any resulting profit or loss belonging entirely to old partners in their old ratio. Increases in assets and decreases in liabilities are gains; decreases in assets and increases in liabilities are losses. The reconstituted firm’s balance sheet then shows all items at their revised values.
Related Reading
Master Revaluation Account Questions With Practice
Revaluation Account questions are pure practice-driven marks — the format is fixed, and speed comes from repetition. ChampionsPrep provides pay-per-use practice sets with fully worked Revaluation Account problems, so Class 12 Commerce students can build accuracy before their board exams.
Test Your Knowledge
Revaluation of Assets and Liabilities on Admission of a Partner
Frequently Asked Questions
Why is revaluation of assets and liabilities necessary on admission of a partner? +
It ensures assets and liabilities are recorded at their true current values, so that any pre-admission gain or loss is credited or charged only to the old partners, not the incoming one.
In what ratio is profit or loss on revaluation shared? +
It is always shared by the old partners in their old profit sharing ratio, regardless of the new profit sharing ratio agreed after admission.
How is an increase in the value of an asset recorded? +
The Asset Account is debited and the Revaluation Account is credited, since it represents a gain.
What happens to an unrecorded liability discovered at the time of admission? +
It is debited to the Revaluation Account and credited to the relevant Liability Account, as it represents a loss to the firm.
Do assets and liabilities appear at their revised values in the new firm's balance sheet? +
Yes. After the Revaluation Account is prepared, the balance sheet of the reconstituted firm shows all assets and liabilities at their revised, post-revaluation values.
AI-powered practice — free to start