
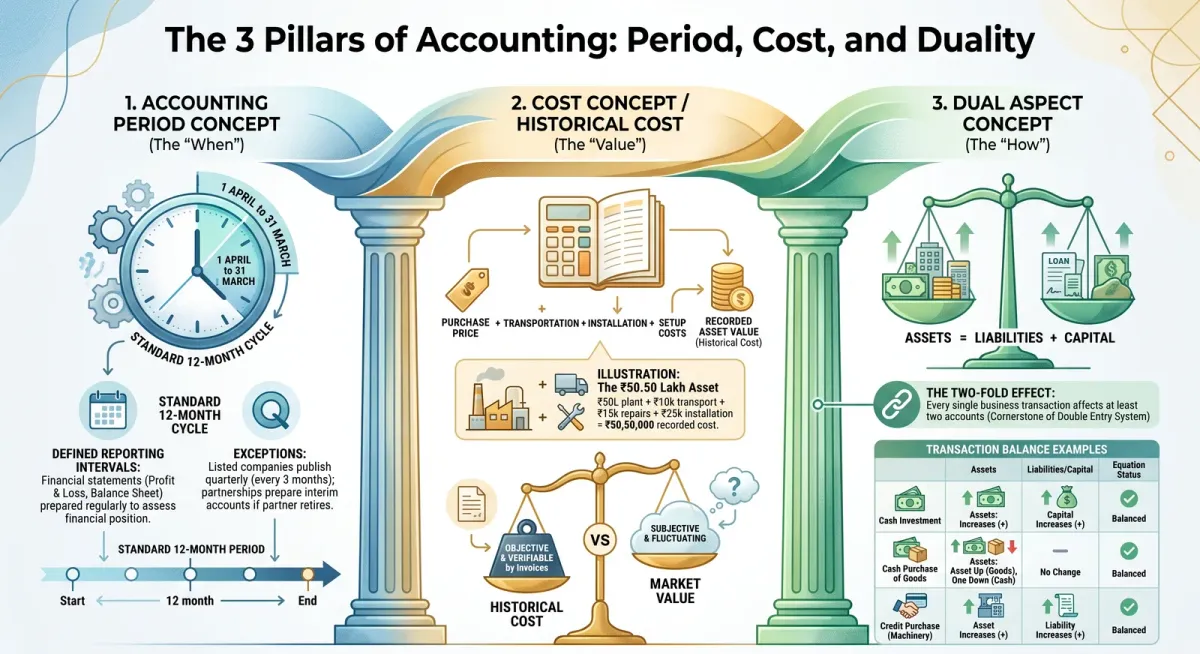
Accounting is built on time-tested principles that bring structure and reliability to financial records. In this guide, we explore three more essential concepts from CBSE Class 11 Accountancy Chapter 2: the Accounting Period Concept, the Cost Concept, and the Dual Aspect Concept — also known as the duality principle.
Each of these addresses a fundamental question: When do we prepare statements? At what value are assets recorded? And how many entries does every transaction require?
1. Accounting Period Concept
What Is an Accounting Period?
An accounting period is the span of time at the end of which the financial statements of a business are prepared. These statements — typically the Profit & Loss Account and the Balance Sheet — reveal:
-
Whether the business has earned a profit or incurred a loss during that period
-
The exact position of assets and liabilities at the end of the period
No business can wait indefinitely to know its financial results. Pricing decisions, hiring plans, borrowing decisions, and tax filings all require periodic financial data. Stakeholders such as investors, creditors, and government tax authorities also need regular updates.
How Long Is an Accounting Period?
Normally, one year is the standard. Under the Companies Act 2013 and the Income Tax Act, companies must prepare annual financial statements. In India, the financial year typically runs from 1 April to 31 March.
However, there are important exceptions:
-
When a partner retires from a partnership firm, an interim set of accounts may be prepared for a shorter period
-
Listed companies (those whose shares trade on stock exchanges) must also publish quarterly results — meaning financial statements for every 3-month period
This flexibility ensures that accounting serves its primary purpose: providing timely and relevant information when decision-makers need it most.
Why This Concept Matters
Without clearly defined accounting periods, comparing results from one time period to the next would be impossible. The concept also underpins revenue recognition and matching — ensuring income and expenses are allocated to the correct year.
2. Cost Concept (Historical Cost Concept)
What Does the Cost Concept State?
The Cost Concept requires that all assets be recorded in the books of accounts at their purchase price — also called historical cost. This total includes:
-
The actual cost of acquisition (purchase price)
-
Transportation charges to bring the asset to the business location
-
Installation expenses
-
Any other cost to make the asset ready for use
Illustration: Shiva Enterprise purchases a used plant for ₹50 lakh. Transport costs to the factory site are ₹10,000. Repair costs to bring the plant into working condition amount to ₹15,000, and installation charges are ₹25,000. The asset is recorded at ₹50,50,000 — the total cost of acquiring and making it operational.
Why Is Historical Cost Preferred?
Historical cost is favoured because it is:
-
Objective — verifiable directly from purchase receipts and invoices
-
Stable — the cost does not change over time as market values do
-
Comparable — allows consistent comparison of asset values across multiple accounting periods
Market values, by contrast, fluctuate unpredictably. The value of a machine may differ between two valuers or between two geographic locations, making comparisons unreliable.
Limitation of the Cost Concept
The main drawback is that historical cost does not reflect the current market worth of a business. During periods of inflation, assets recorded at their original cost may be significantly undervalued compared to what they could fetch today. This situation can lead to hidden profits — the business looks less valuable than it actually is in real terms.
3. Dual Aspect Concept (Duality Principle)
The Foundation of All Accounting
The Dual Aspect Concept is often called the cornerstone of accounting. It states that every business transaction has a two-fold effect and therefore affects at least two accounts simultaneously.
This concept is expressed through the fundamental Accounting Equation:
Assets = Liabilities + Capital
This equation shows that every resource a business owns (assets) is financed either by the owner (capital) or by outside parties (liabilities). Crucially, the two sides of this equation are always equal.
Understanding Through Three Examples
Example 1 — Cash Investment: Ram starts a business by investing ₹50,00,000 in cash.
-
Cash / Asset increases by ₹50,00,000
-
Capital increases by ₹50,00,000
-
Equation: ₹50,00,000 = ₹0 + ₹50,00,000 ✓
Example 2 — Cash Purchase of Goods: The firm purchases goods worth ₹10,00,000 on cash.
-
Stock (asset) increases by ₹10,00,000
-
Cash (asset) decreases by ₹10,00,000
-
Total assets remain unchanged; the equation still holds ✓
Example 3 — Credit Purchase of Machinery: The firm buys machinery worth ₹30,00,000 on credit from Reliable Industries.
-
Machinery (asset) increases by ₹30,00,000
-
Creditor / Liability increases by ₹30,00,000
-
Equation: Assets rise on both sides — balance maintained ✓
Why It Matters
Every transaction creates a debit in one account and a credit in another. This two-fold recording is the heart of the Double Entry System of bookkeeping (covered in Chapter 3). If the two sides of the accounting equation ever fail to balance, it signals that an error has been made somewhere in the records — making error detection much easier.
The Dual Aspect Concept also explains why the Balance Sheet always balances: total assets always equal total liabilities plus capital, no matter how many transactions occur.
Quick Reference Summary
| Concept | Key Rule | Main Benefit |
|---|---|---|
| Accounting Period | Prepare statements at regular intervals | Enables timely decision-making |
| Cost Concept | Record assets at purchase price | Ensures objectivity and verifiability |
| Dual Aspect | Every transaction affects two accounts | Foundation of the Double Entry System |
Related Reading on ChampionsPrep
-
Previous: Business Entity, Money Measurement & Going Concern Concepts
-
Next: Revenue Recognition and Matching Concept — Class 11 Guide
🎯 Master Every Concept with ChampionsPrep
Still confused about accounting concepts? Get instant answers to your doubts with ChampionsPrep — the AI-powered doubt resolution platform built specifically for Class 11 and Class 12 Commerce students.
👉 Start learning smarter at https://app.championsprep.in
Test Your Knowledge
Interactive Practice: Identify the Accounting Concept

Accounting Period, Cost Concept & Dual Aspect Explained | Class 11 Accountancy
Frequently Asked Questions
What is the standard accounting period in India? +
In India, the standard accounting period is one financial year, from 1 April to 31 March, as required by the Companies Act 2013 and the Income Tax Act. Listed companies must additionally publish quarterly results every three months.
Why is historical cost preferred over current market value for recording assets? +
Historical cost is objective and verifiable from purchase documents, and it remains stable over time. Market values fluctuate and can vary between valuers, making them less reliable for consistent financial recording.
What costs are included in the historical cost of an asset? +
Historical cost includes the purchase price, transportation charges, installation costs, repair costs necessary to make the asset operational, and any other expenses incurred before the asset is ready for its intended use.
What is the Dual Aspect Concept in simple terms? +
The Dual Aspect Concept states that every transaction simultaneously affects two accounts — one is debited and the other is credited. This maintains the balance of the accounting equation: Assets = Liabilities + Capital.
How does the Dual Aspect Concept relate to the Double Entry System? +
The Dual Aspect Concept provides the theoretical basis for Double Entry Bookkeeping. Since every transaction has two effects, both must be recorded, ensuring complete and arithmetically verifiable books of accounts.
AI-powered practice — free to start