
Two of the most practically important concepts in accounting — the Revenue Recognition Concept and the Matching Concept — directly determine how profits and losses are calculated for any given period. Get these wrong, and a company’s financial statements can paint a completely false picture of its financial health.
In this guide, we break down both concepts clearly using real-life examples, making them easy to understand and apply for your Class 11 board exams and competitive tests like CUET.
1. Revenue Recognition (Realisation) Concept
What Is Revenue?
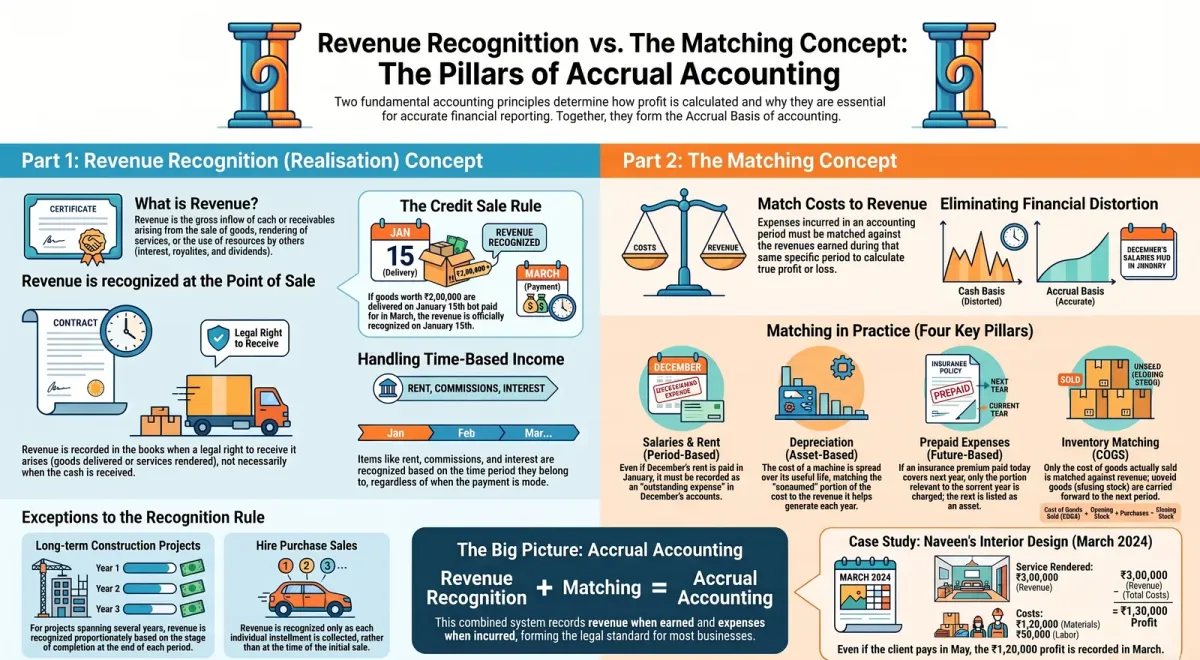
Before we can talk about when to recognise revenue, we need to be clear about what revenue actually is. Revenue is the gross inflow of cash arising from:
-
Sale of goods and services by the enterprise
-
Use by others of the enterprise’s resources — generating interest, royalties, and dividends
Revenue refers to gross inflow, not to profit. Profit is what remains after deducting all related expenses from revenue.
When Is Revenue Recognised?
This is the core question addressed by the Realisation Concept. Revenue is recognised — that is, recorded in the books — only when a legal right to receive it arises.
In practical terms:
Revenue is recognised at the point of sale — when goods are delivered or a service is rendered — not when cash is received.
Example: On 15 January, a firm delivers goods worth ₹2,00,000 on credit to a customer. The customer pays in March.
-
Revenue is recognised on 15 January (date of delivery/sale)
-
NOT in March when cash arrives
This is why credit sales count as revenue even though no cash has changed hands at the time. The legal right to receive the money already exists.
Time-Based Income: A Special Case
For income such as rent, commission, and interest, revenue is recognised on a time basis rather than a transaction basis:
-
Rent for March 2024, even if received in April 2024, belongs to the financial year ending 31 March 2024
-
Interest received in advance in March 2024 for the period of April 2024 onwards belongs to the next financial year
This prevents distortion of financial results simply due to timing differences in cash receipts.
Exceptions to the General Rule
The Revenue Recognition Concept has two notable exceptions:
-
Long-term construction contracts (projects taking 2–3 years): Revenue is recognised proportionately based on the stage of completion at the end of each accounting period, not just when the contract is finished.
-
Hire purchase sales: Revenue is recognised as each instalment is collected, rather than recording the full sale price at the time the goods are handed over.
2. Matching Concept
What Does the Matching Concept State?
The Matching Concept states that expenses incurred in an accounting period must be matched against the revenues earned during the same period. In other words:
You cannot deduct the expenses of one period from the revenue of a different period.
Revenue and the expenses incurred to earn that revenue must always belong to the same accounting period. This is how an accurate profit or loss figure is arrived at.
Why This Concept Is Essential
Without matching, financial results become meaningless. If salaries paid in January 2025 for work done in December 2024 are charged to January 2025, the profit figures for both December and January are distorted. The Matching Concept eliminates this distortion.
Matching in Practice — Four Key Examples
1. Salaries and Rent (Period-Based Expenses) These are matched to the period they relate to, not when they are paid. December 2024 salary is a December expense — even if the payment reaches employees in January 2025, it is recorded as an outstanding expense in December’s accounts.
2. Depreciation (Asset-Based Matching) The cost of a machine is not charged as a single lump expense in the year of purchase. Instead, it is spread over the machine’s useful life. Each year, the portion of cost “consumed” to earn that year’s revenue is charged as depreciation — matching the cost to the period that benefited from its use.
3. Cost of Goods Sold (Inventory Matching) When calculating profit, only the cost of goods actually sold is matched against the revenue earned from those sales. Unsold goods are carried forward as closing stock — their cost is deferred to the period in which they will be sold.
Cost of Goods Sold = Opening Stock + Purchases − Closing Stock
4. Prepaid Expenses (Future Period Costs) If insurance premium is paid in January 2025 covering the period up to December 2025, only the portion relevant to the current accounting year (April 2024 to March 2025) is charged as expense. The remaining portion is shown as a prepaid expense — an asset — and matched against the next year’s revenue.
Revenue Recognition + Matching = Accrual Accounting
Together, these two concepts form the backbone of accrual-based accounting — the system that most businesses are legally required to follow. Under accrual accounting:
-
Revenue is recorded when earned (not when cash is received)
-
Expenses are recorded when incurred (not when cash is paid)
This creates a far more accurate picture of financial performance than simply tracking when cash moves in and out.
Real-World Example: Both Concepts Together
Naveen’s Interior Design firm completes a project in March 2024, billing the client ₹3,00,000. Payment arrives in May 2024. Material costs of ₹1,20,000 and labour wages of ₹50,000 were incurred in March 2024.
Applying both concepts:
-
Revenue (₹3,00,000) is recognised in March 2024 — service rendered
-
Material cost (₹1,20,000) + labour (₹50,000) are matched to March 2024
-
Profit for March 2024: ₹3,00,000 − ₹1,70,000 = ₹1,30,000
This accurately reflects what was earned and what was spent in the same period.
Related Reading on ChampionsPrep
-
Previous: Accounting Period, Cost Concept & Dual Aspect Explained
-
Related: Cash Basis vs Accrual Basis of Accounting & Accounting Standards
🎯 Get Exam-Ready with ChampionsPrep
Preparing for your Class 11 Accountancy board exam or CUET? ChampionsPrep offers chapter-wise practice questions and AI-powered doubt resolution — designed specifically for Commerce students.
👉 Practise now at https://app.championsprep.in
Test Your Knowledge
Interactive Practice: Match the Fundamental Concept
Revenue Recognition and Matching Concept | Class 11 Accountancy Chapter 2
Frequently Asked Questions
When is revenue recognised according to the Realisation Concept? +
Revenue is recognised when a legal right to receive it arises — typically when goods are delivered or a service is rendered. For time-based income like rent and interest, it is recognised on a time basis irrespective of when cash changes hands.
Are credit sales included in revenue even before cash is received? +
Yes. Under the Revenue Recognition Concept, credit sales are treated as revenue on the date of delivery or service completion, not on the date of payment. The legal right to receive the amount already exists at the point of sale.
What is the Matching Concept in accounting? +
The Matching Concept requires that expenses incurred in an accounting period must be matched with revenues earned during the same period. This ensures that the profit or loss calculated for a period accurately reflects the actual activity of that period.
How does depreciation illustrate the Matching Concept? +
Depreciation spreads the cost of a fixed asset over its useful life. Each year, the portion of cost related to that year's usage is charged against that year's revenue — matching the asset's cost to the periods that benefit from its use.
What is the difference between Revenue Recognition and Matching Concepts? +
Revenue Recognition determines when income is recorded. The Matching Concept determines which expenses are set against that income in the same period. Together, they ensure the Profit & Loss Account gives a true and fair picture of business performance.
AI-powered practice — free to start