
The Cash Flow Statement answers a question that the Income Statement cannot: where did the money actually go? A company can be profitable on paper and still run out of cash. This statement explains why — and it is one of the most practical, logical, and consistently examined topics in CBSE Class 12 Accountancy.
What Is a Cash Flow Statement?
As per Accounting Standard 3 (AS-3), a Cash Flow Statement is a financial statement that shows the inflows and outflows of cash and cash equivalents during an accounting period.
It is prepared on a cash basis — meaning it shows actual cash received and paid, not income earned or expenses accrued.
Four Questions It Answers
| Question | What It Reveals |
|---|---|
| Where did cash come from? | Sources of cash during the period |
| Where did cash go? | Uses of cash during the period |
| Why is profit different from cash? | Effect of non-cash items and timing differences |
| Can the company meet its obligations? | Real liquidity, not just accounting liquidity |
Cash vs Cash Equivalents: Know the Difference
Cash Includes:
-
Physical currency and coins
-
Bank balances in current and savings accounts
-
Cash-in-hand at the business
Cash Equivalents Include:
-
Short-term, highly liquid investments
-
Maturity period of 3 months or less from acquisition date
-
Readily convertible to a known amount of cash with negligible risk of value change
-
Examples: Treasury bills, commercial paper, money market instruments
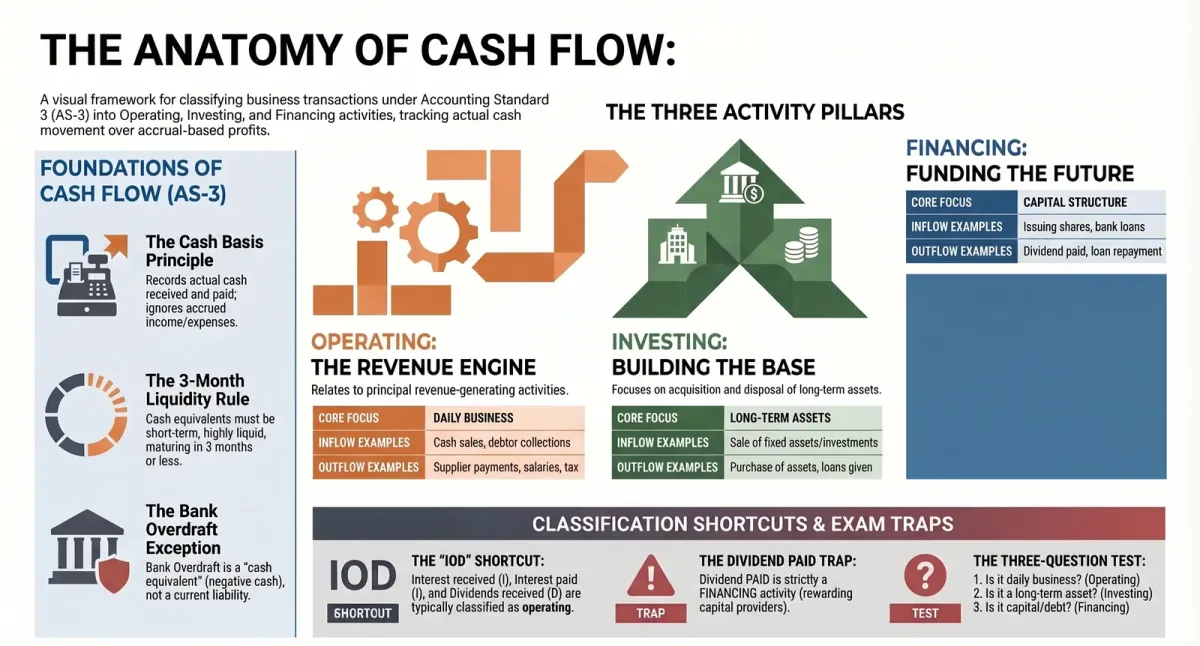
Critical rule: Bank overdraft is treated as a cash equivalent (negative cash) in the Cash Flow Statement — not as a current liability. This is one of the most commonly tested exceptions in both board exams and CA Foundation MCQs.
The Three Activity Classifications
AS-3 requires every cash transaction to be classified into one of three categories. Getting this classification right is the foundation of the entire statement.
Activity 1: Operating Activities
These are the principal revenue-generating activities of the business — the day-to-day core operations.
Cash Inflows:
-
Cash sales to customers
-
Collections from debtors (trade receivables)
-
Interest received (may be classified here or under Investing)
-
Dividend received (may be classified here or under Investing)
Cash Outflows:
-
Payments to suppliers for goods and services
-
Salaries, wages, and other operating expenses paid
-
Interest paid (may be classified here or under Financing)
-
Income tax paid
The key test: Does this transaction relate to the company’s daily business of producing and selling goods or services? If yes → Operating.
Activity 2: Investing Activities
These involve the acquisition and disposal of long-term assets and investments — decisions about how the company is building or restructuring its asset base.
Cash Inflows:
-
Sale of fixed assets (property, plant, equipment)
-
Sale of investments (shares, debentures held)
-
Interest received (if not classified under Operating)
-
Dividend received (if not classified under Operating)
-
Loan repayments received from others
Cash Outflows:
-
Purchase of fixed assets
-
Purchase of long-term investments
-
Loans given to subsidiaries or other parties
The key test: Does this transaction involve a long-term asset or investment? If yes → Investing.
Activity 3: Financing Activities
These relate to changes in the size and composition of the company’s capital and long-term borrowings — how the company funds itself.
Cash Inflows:
-
Issue of equity or preference shares
-
Issue of debentures
-
Long-term loans taken from banks or financial institutions
Cash Outflows:
-
Redemption of preference shares or debentures
-
Repayment of long-term loans
-
Dividend paid to shareholders
-
Interest paid (if not classified under Operating)
The key test: Does this transaction involve raising or repaying capital or long-term debt? If yes → Financing.
The Optional Classification Items: Interest and Dividend
AS-3 gives flexibility on where interest received, dividend received, and interest paid are classified. For CBSE purposes, the most commonly applied treatment is:
| Transaction | Standard Classification for Board Exams |
|---|---|
| Interest received | Operating Activities |
| Dividend received | Operating Activities |
| Interest paid | Operating Activities |
| Dividend paid | Financing Activities |
Exam trap: Dividend paid is Financing, not Operating. This is one of the most frequently tested classification rules — and the most frequently confused.
Interactive Activity Classification Drill
Test your mastery of AS-3 classification by sorting each scenario into Operating, Investing, or Financing activities.
AS-3 Cash Flow Activity Classifier
Quick Classification Shortcuts
The IOD Rule (CA Foundation Favourite)
-
Interest received → Operating
-
Dividend received → Operating
-
Interest paid → Operating
-
Dividend paid → Financing
The Three-Question Test
-
Does it relate to daily business operations? → Operating
-
Does it involve a long-term asset or investment? → Investing
-
Does it involve capital raising or repayment? → Financing
Apply these in order. The first “yes” determines the category.
Side-by-Side Summary
| Activity | Core Focus | Inflow Examples | Outflow Examples |
|---|---|---|---|
| Operating | Daily business | Cash sales, debtor collections | Supplier payments, salaries, tax |
| Investing | Long-term assets | Asset sale, investment sale | Asset purchase, loans given |
| Financing | Capital structure | Share issue, loans taken | Dividend paid, loan repayment |
Why the Cash Flow Statement Matters Beyond the Exam
A company reporting high profits can still be cash-poor if:
-
Most sales are on credit (debtors are rising)
-
Cash is being heavily deployed in new assets
-
Debt repayments are large
The Cash Flow Statement is the only financial statement that captures all three of these realities simultaneously. That is why it is a mandatory statement under AS-3 — and why understanding it deeply is rewarded in both board exams and in practice.
What’s Next?
In Part 2 , we cover the Indirect Method for preparing Operating Activities — the step-by-step process of starting from net profit and adjusting for non-cash items, with the PADLA mnemonic that makes each adjustment logical rather than memorised.
AI-powered practice — free to start