

Profit and Loss Appropriation Account: Meaning, Format & How to Prepare It
In a sole proprietorship, life is simple — whatever profit the business earns belongs entirely to the one owner, and it is transferred directly to their capital account. A partnership firm, however, has multiple stakeholders, each entitled to their own salary, interest on capital, commission, or share of profit as per the partnership deed. To handle this more complex distribution, accountants prepare a special account called the Profit and Loss Appropriation Account — a core topic in CBSE Class 12 Accountancy.
What Is a Profit and Loss Appropriation Account?
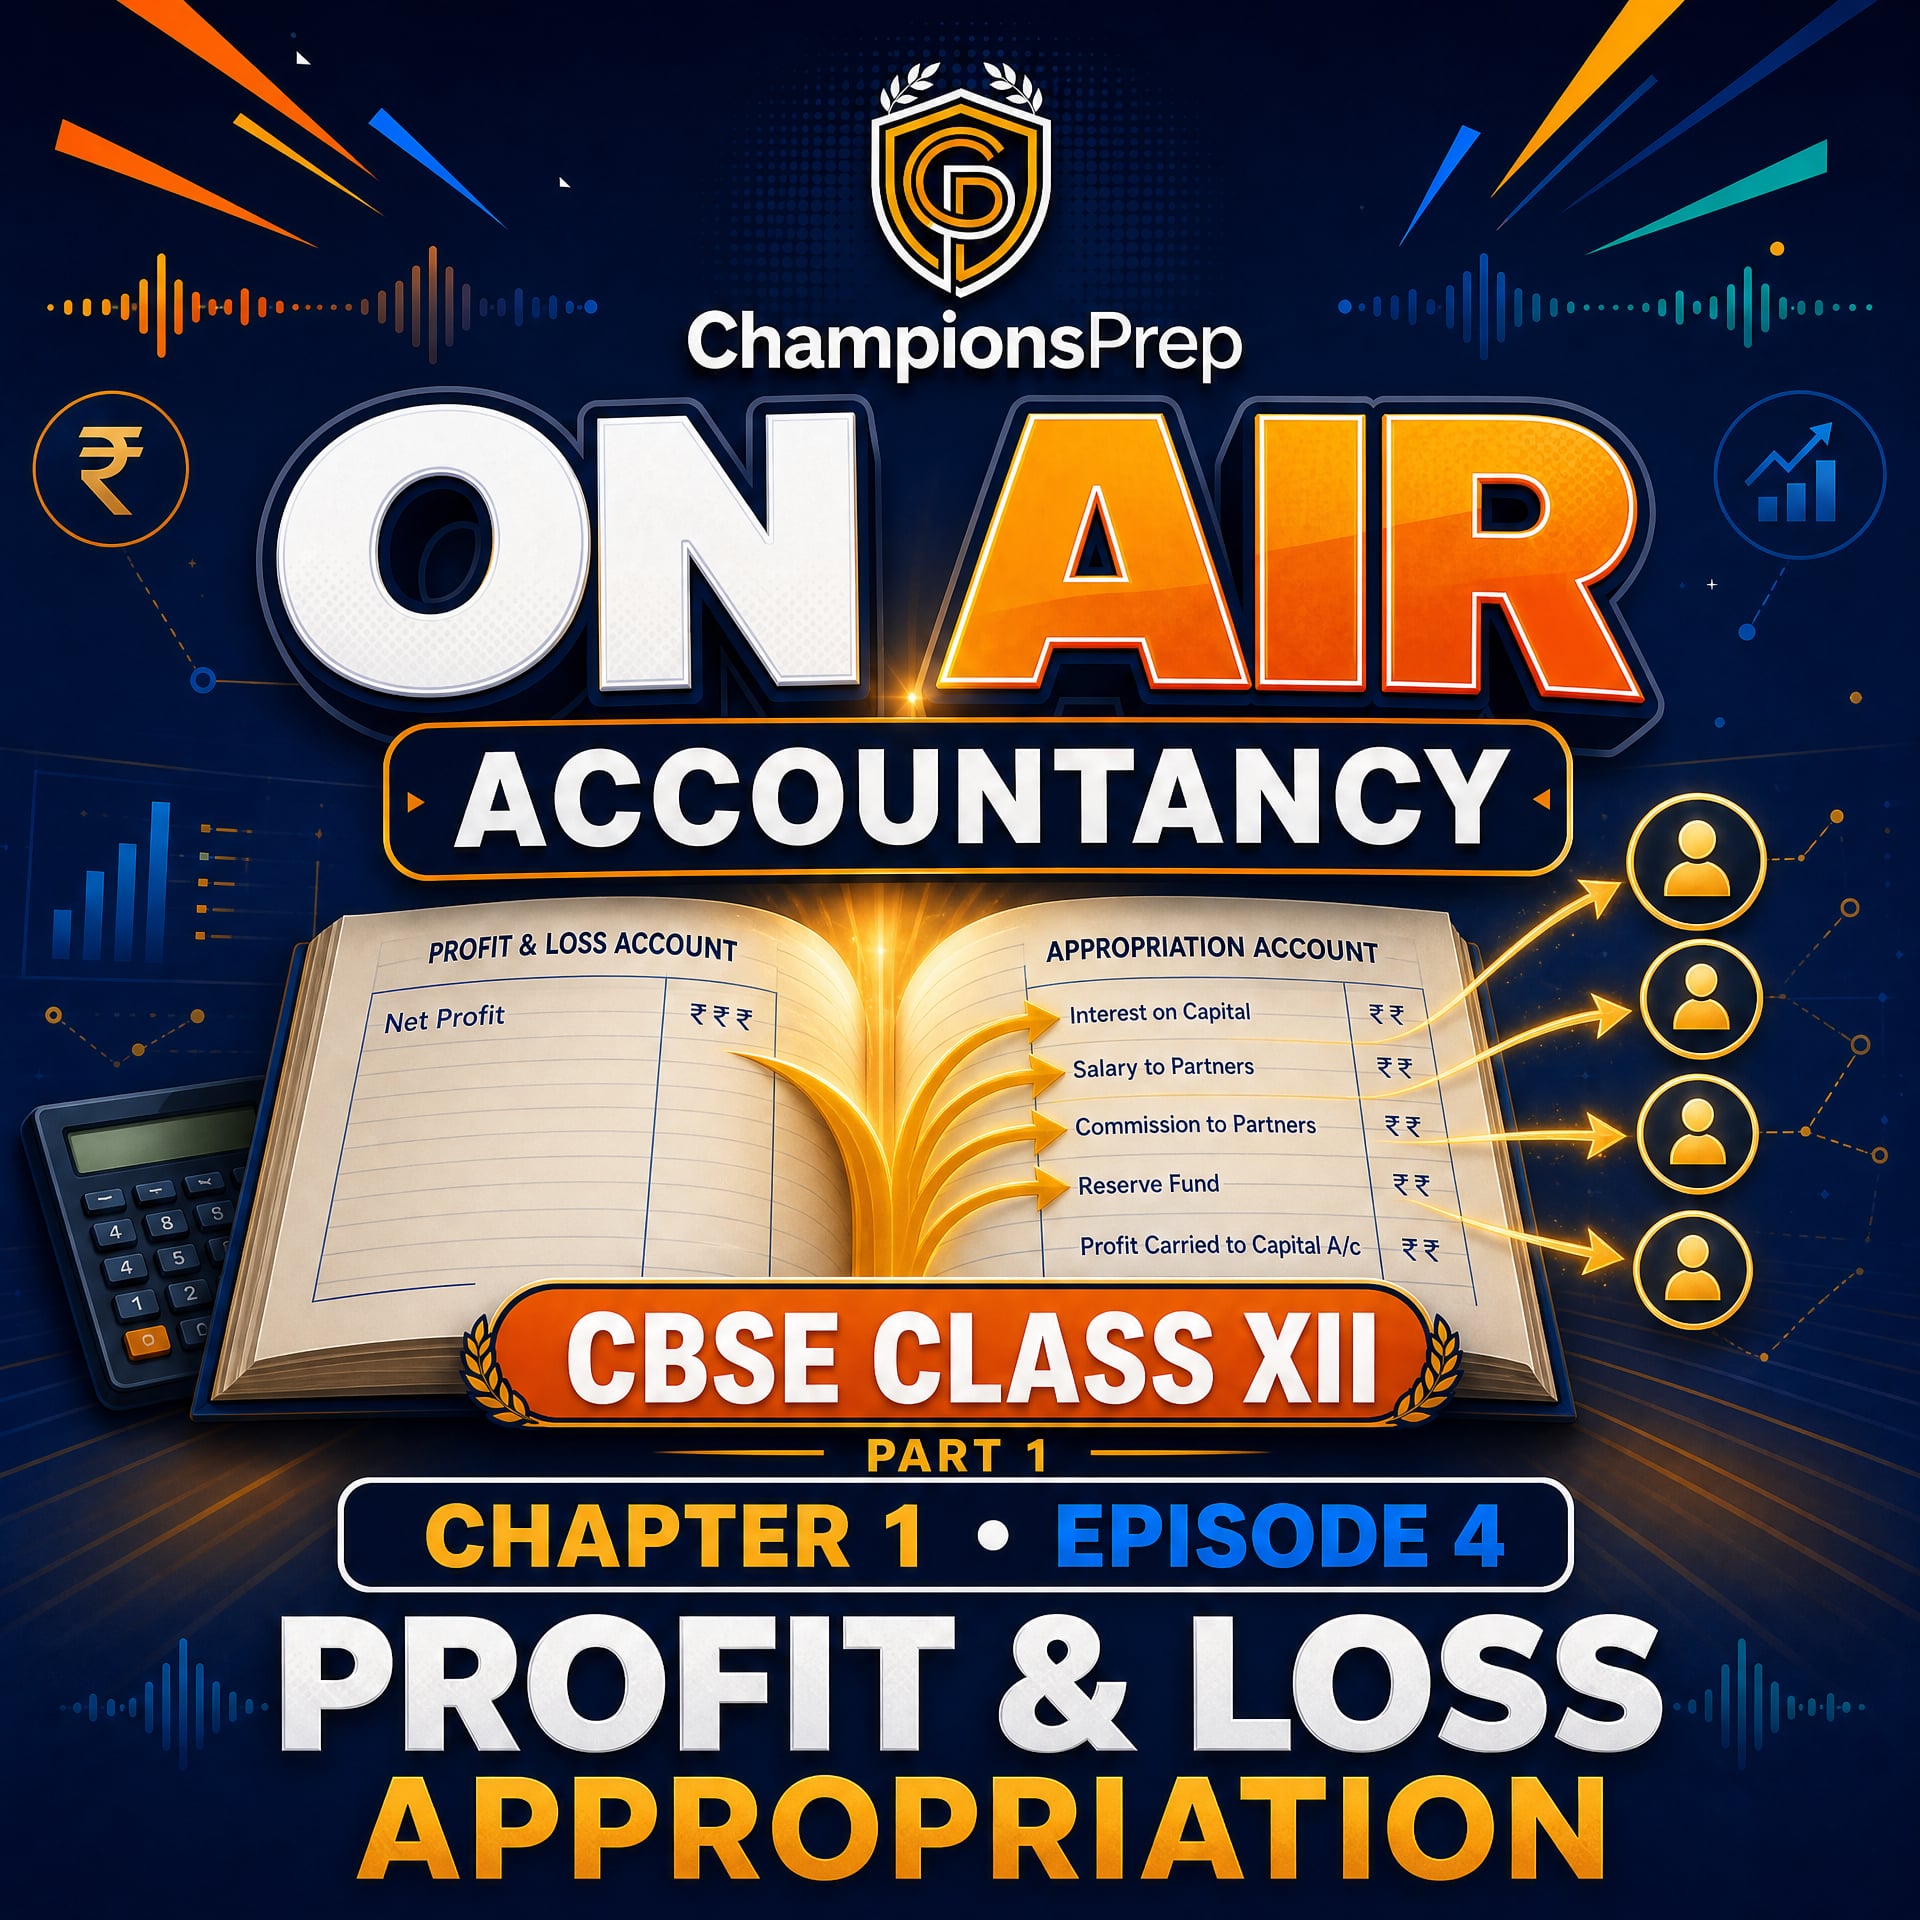
The Profit and Loss Appropriation Account is essentially an extension of the firm's regular Profit and Loss Account. While the Profit and Loss Account calculates the overall net profit or loss of the business, the Appropriation Account shows how that profit is divided or "appropriated" among the partners. It accounts for all the special adjustments unique to partnerships — interest on capital, interest on drawings, partners' salaries, and commissions — before arriving at the final figure to be split among partners in their agreed profit-sharing ratio.
Why Is It Necessary?
Without this account, it would be difficult to clearly show, in one place, how a firm's profit gets divided after accounting for each partner's individual entitlements. It creates transparency and a clean audit trail, both of which matter for partners and for anyone reviewing the firm's books.
Format of the Profit and Loss Appropriation Account
| Debit Side | Credit Side |
|---|---|
| Profit and Loss A/c (if there is a loss) | Profit and Loss A/c (if there is profit) |
| Interest on Capital | Interest on Drawings |
| Salary to Partner | Partners' Capital/Current A/cs (share of loss) |
| Commission to Partner | |
| Partners' Capital/Current A/cs (share of profit) |
The account always begins with the net profit or net loss brought forward from the regular Profit and Loss Account.
Key Journal Entries
To prepare this account correctly, you need to know the underlying journal entries:
- Transferring net profit: Profit and Loss A/c Dr. → To Profit and Loss Appropriation A/c
- Allowing interest on capital: Interest on Capital A/c Dr. → To Partners' Capital/Current A/cs
Then: Profit and Loss Appropriation A/c Dr. → To Interest on Capital A/c
- Charging interest on drawings: Partners' Capital/Current A/cs Dr. → To Interest on Drawings A/c
Then: Interest on Drawings A/c Dr. → To Profit and Loss Appropriation A/c
- Allowing partner's salary: Salary to Partner A/c Dr. → To Partners' Capital/Current A/cs
Then: Profit and Loss Appropriation A/c Dr. → To Salary to Partner's A/c
- Crediting partner's commission: Commission to Partner A/c Dr. → To Partners' Capital/Current A/cs
Then: Profit and Loss Appropriation A/c Dr. → To Commission to Partners' Capital/Current A/c
- Distributing final profit or loss: Profit and Loss Appropriation A/c Dr. → To Partners' Capital/Current A/cs (if profit); or the reverse entry if there's a loss.
An important rule to remember: if the firm has incurred a net loss for the year, no interest on capital, salary, or other remuneration is allowed to any partner — these are only payable out of profits.
Profit and Loss Appropriation Account: Meaning, Format & Solved Example
Solved Example
Consider a firm with two partners, Rakesh and Meera, sharing profits and losses equally, with capitals of ₹6,00,000 and ₹4,00,000 respectively. The partnership deed provides for:
- Interest on capital at 6% per annum
- A monthly salary of ₹5,000 to Meera
- Interest on drawings: ₹1,200 for Rakesh and ₹800 for Meera
The firm's net profit for the year, before these adjustments, is ₹1,50,000.
Step 1 — Calculate interest on capital:
Rakesh: 6% of ₹6,00,000 = ₹36,000
Meera: 6% of ₹4,00,000 = ₹24,000
Step 2 — Calculate Meera's salary:
₹5,000 × 12 months = ₹60,000
Step 3 — Prepare the Appropriation Account:
Debit side: Interest on Capital (₹36,000 + ₹24,000 = ₹60,000), Meera's Salary (₹60,000), and the balance transferred as profit to partners.
Credit side: Net Profit brought forward (₹1,50,000) and Interest on Drawings (₹1,200 + ₹800 = ₹2,000).
Total credits = ₹1,52,000. Total appropriations before profit distribution = ₹1,20,000 (interest on capital + salary). Remaining profit to distribute = ₹1,52,000 − ₹1,20,000 = ₹32,000, split equally: ₹16,000 to Rakesh and ₹16,000 to Meera.
This final figure is what gets transferred to each partner's capital or current account, completing the appropriation process.
Key Takeaways
- The Profit and Loss Appropriation Account shows how a firm's profit is distributed among partners after all agreed adjustments.
- It starts with the net profit or loss and adjusts for interest on capital, interest on drawings, salary, and commission.
- In a loss year, no interest on capital or salary is allowed to partners.
- The final balance is transferred to partners' capital or current accounts in their profit-sharing ratio.
Related Reading on ChampionsPrep
- Link "interest on capital" to: Interest on Capital in Partnership Accounts: Rules, Formula & Solved Example
- Link "interest on drawings" to: Interest on Drawings: Methods of Calculation Explained
- Link "capital and current accounts" to: Fixed vs Fluctuating Capital Accounts: Difference, Format & Examples
- Link "guarantee of minimum profit" to: Guarantee of Minimum Profit to a Partner: Meaning, Treatment & Example
Build Exam Confidence With Practice
Preparing the Profit and Loss Appropriation Account correctly is one of the highest-weightage skills in the CBSE Class 12 Accountancy board exam. Get step-by-step practice questions and instant solutions at https://app.championsprep.in — pay only for the practice you need.
Test Your Knowledge
Interactive Practice: Classify the Accounting Element
Frequently Asked Questions
Why do partnership firms prepare a Profit and Loss Appropriation Account? +
It is prepared to clearly show how the firm's net profit is distributed among partners after adjusting for interest on capital, interest on drawings, salary, and commission, as agreed in the partnership deed.
What is shown on the debit side of the Profit and Loss Appropriation Account? +
The debit side typically shows interest on capital, salary to partners, commission to partners, and the share of profit transferred to partners' capital or current accounts.
Is interest on capital allowed if the firm makes a loss? +
No. Interest on capital, salary, or any other remuneration is not allowed to partners in a year when the firm incurs a net loss.
What is the starting point of a Profit and Loss Appropriation Account? +
It starts with the net profit or net loss as calculated in the firm's regular Profit and Loss Account.
Where does the final distributable profit get transferred? +
The final balance, representing distributable profit or loss, is transferred to the partners' capital or current accounts in their agreed profit-sharing ratio.
Keep practising Accountancy
AI-powered feedback and structured revision for Accountancy — free to start, at your own pace.
AI-powered practice — free to start