
Interest on Capital in Partnership Accounts: Rules, Formula & Solved Example
Imagine two partners contribute very different amounts of capital to a firm but agree to share profits equally. Is that fair to the partner who put in more money? This is precisely the situation that interest on capital is designed to address in partnership accounting. It's a recurring topic in CBSE Class 12 Accountancy, and questions on it almost always involve calculations with capital additions or withdrawals during the year — so getting the method right matters.
What Is Interest on Capital?
Interest on capital is compensation credited to a partner for the capital they've invested in the firm, calculated at an agreed rate for the period the capital remained invested during the year. It is typically provided for in two common situations:
- When partners contribute unequal amounts of capital but share profits equally.
- When capital contribution is the same, but the profit-sharing ratio is unequal.
When Is Interest on Capital Allowed?
This is a rule students often get wrong: no partner has an automatic right to interest on capital. It is allowed only when the partnership deed expressly provides for it. If the deed is silent, no interest on capital is credited at all, no matter how large a partner's capital contribution is.
How Is Interest on Capital Calculated?
The basic formula is straightforward:
Interest on Capital = Capital × Rate × Time (in years)
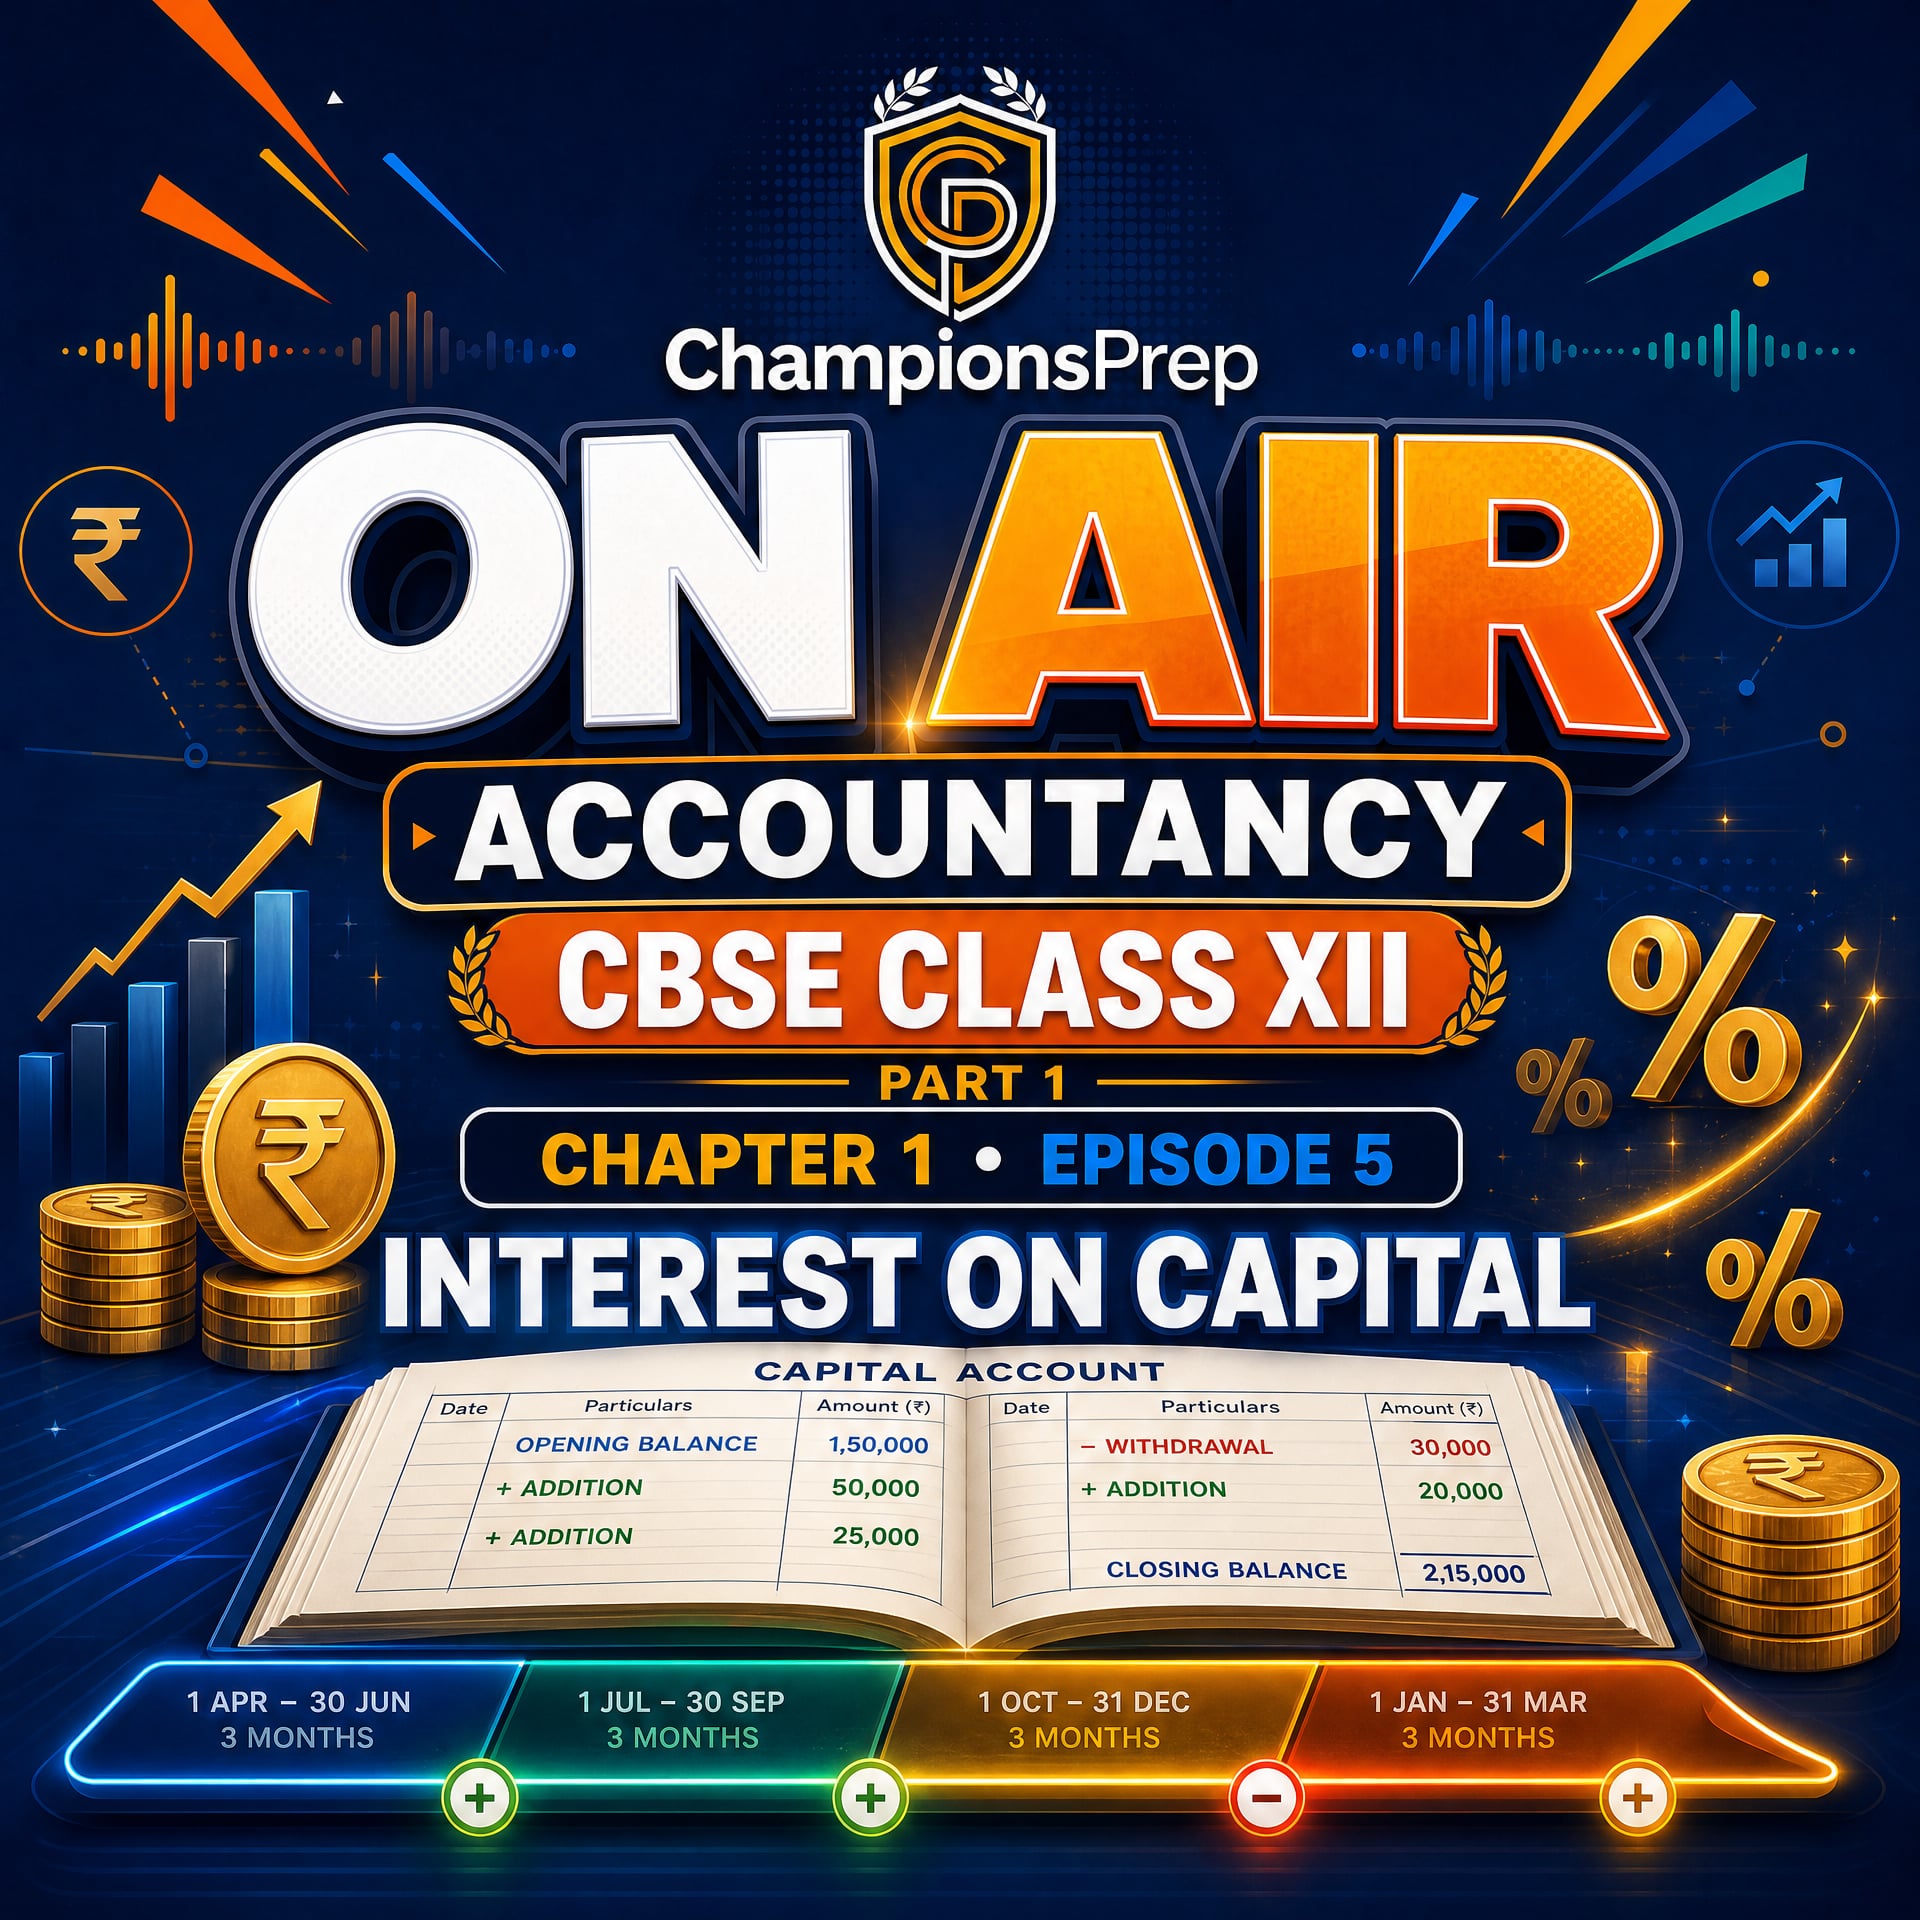
But real exam questions rarely stop at a simple, unchanging capital balance for the whole year. You need to adjust for any additions or withdrawals of capital during the year:
- On the opening balance of the capital account, interest is calculated for the full year.
- On additional capital introduced during the year, interest is calculated only from the date of introduction to the end of the financial year.
- On withdrawal of capital, interest is calculated on the original capital up to the date of withdrawal, and then on the reduced balance for the remaining period.
Interest on Capital in Partnership Accounts: Rules, Formula & Solved Example
Worked Example
Suppose two partners, Farah and Karan, have opening capital balances of ₹4,00,000 and ₹3,00,000 respectively on April 1. On July 1, Farah introduces an additional ₹1,00,000, and on October 1, Karan withdraws ₹50,000. Interest on capital is agreed at 6% per annum. Let's calculate the interest due to each for the year ending March 31.
For Farah:
- On ₹4,00,000 for the full 12 months: 4,00,000 × 6% = ₹24,000
- On additional ₹1,00,000 for 9 months (July to March): 1,00,000 × 6% × 9/12 = ₹4,500
- Total interest for Farah = ₹28,500
For Karan:
- On ₹3,00,000 for 6 months (April to September): 3,00,000 × 6% × 6/12 = ₹9,000
- On the reduced balance of ₹2,50,000 for the remaining 6 months (October to March): 2,50,000 × 6% × 6/12 = ₹7,500
- Total interest for Karan = ₹16,500
Notice how each change in capital creates a new "slab" for calculation — this is the technique tested most often in board exams.
What Happens When Profit Is Not Enough?
Here's a nuance many students miss: interest on capital is allowed only out of profits. If the firm's profit for the year is less than the total interest on capital due to all partners, the available profit is distributed among partners strictly in the ratio of their interest on capital entitlements — not paid out in full.
For example, if Partner A is entitled to ₹12,000 and Partner B to ₹16,000 as interest on capital (a total of ₹28,000), but the firm's profit is only ₹14,000, this amount is split in the ratio 12,000 : 16,000, i.e., 3 : 4. Partner A receives ₹6,000 and Partner B receives ₹8,000. And if the firm incurs a loss for the year, no interest on capital is allowed at all — none of the partners receive anything under this head.
Finding Opening Capital When It Isn't Given
Some questions give you the closing capital and ask you to work backward to find the opening capital before calculating interest. The adjustment process looks like this:
Closing Capital + Drawings during the year − Share of Profit already credited − Additional capital introduced during the year = Opening Capital
This reverse calculation is a common trap in longer numerical problems, so always check whether the capital figure given is an opening or closing balance before applying the interest formula.
Key Takeaways
- Interest on capital is allowed only when the partnership deed expressly provides for it.
- Adjust the calculation for any additional capital introduced or capital withdrawn during the year.
- If profit is insufficient to cover total interest on capital, the available profit is distributed in the ratio of interest entitlements.
- No interest on capital is allowed at all if the firm incurs a net loss.
Related Reading on ChampionsPrep
- Link "Profit and Loss Appropriation Account" to: Profit and Loss Appropriation Account: Meaning, Format & Example
- Link "interest on drawings" to: Interest on Drawings: Methods of Calculation Explained
- Link "fixed and fluctuating capital accounts" to: Fixed vs Fluctuating Capital Accounts: Difference, Format & Examples
- Link "partnership deed" to: What Is Partnership? Meaning, Features & Partnership Deed Explained
Practice Interest on Capital Problems Now
Interest on capital calculations with multiple capital changes are a favourite in CBSE board papers. Build speed and accuracy with topic-wise problem sets at https://app.championsprep.in, priced pay-per-use so you only pay for the practice you actually need.
Test Your Knowledge
Interactive Classifier: Capital vs Revenue Expenditure
Frequently Asked Questions
Is interest on capital compulsory for every partnership firm? +
No. Interest on capital is allowed only when the partnership deed specifically provides for it. Without such a provision, no partner receives interest on capital.
How is interest calculated when a partner introduces additional capital during the year? +
Interest on the additional capital is calculated only for the period from the date it was introduced to the last day of the financial year, not for the whole year.
What happens if a firm's profit is less than the total interest on capital due? +
The available profit is distributed among the partners in the ratio of their respective interest on capital entitlements, rather than paying the full interest amount to each.
Is interest on capital allowed if the firm makes a loss? +
No. Interest on capital is allowed only out of profits. If the firm incurs a loss during the year, no interest on capital is credited to any partner.
How do you calculate interest on capital when part of the capital is withdrawn during the year? +
Interest is calculated on the original capital balance up to the date of withdrawal, and then on the reduced balance for the remaining part of the year.
Keep practising Accountancy
AI-powered feedback and structured revision for Accountancy — free to start, at your own pace.
AI-powered practice — free to start